
Most people evaluate real estate the same way they evaluate a car.
They look at the monthly payment.
They ask whether the payment fits their budget.
Then they decide whether they can afford it.
That may be enough when purchasing something for personal use.
It is not enough when evaluating an investment.
An investment property is not simply a house with a mortgage. It is a financial asset with income, operating expenses, financing costs, tax implications, equity growth, appreciation potential, and risk.
The real question is not:
Can I afford the payment?
The better question is:
Will this asset actually build wealth?
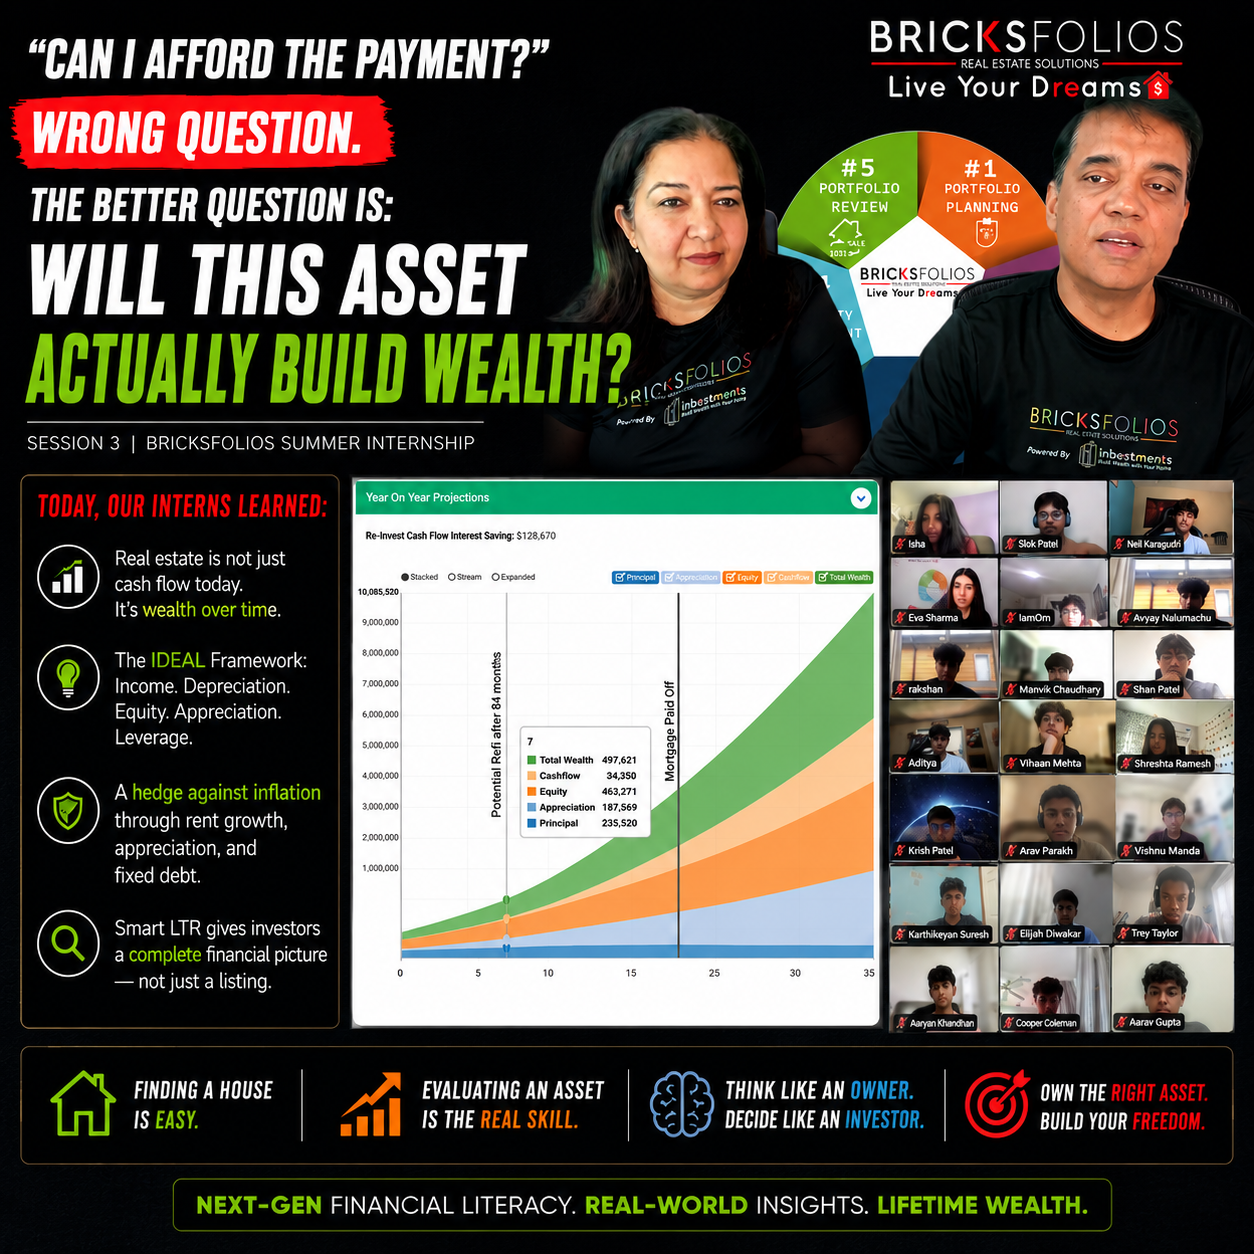
That distinction was at the center of Session 3 of the BricksFolios Summer Business Internship.
Our students analyzed a real rental property using BricksFolios Smart LTR. They learned how professional investors move beyond listing prices and mortgage calculators to understand how an asset may perform over time.
For many of the high school students, these ideas were completely new.
That was the point.
Financial literacy should not begin after someone earns their first six-figure salary, buys their first home, or makes their first expensive investment mistake.
It should begin early.
It should teach young people how to evaluate opportunities, question assumptions, and understand how ownership creates wealth.
What Is the Most Important Question When Evaluating a Rental Property?
The most important question is not whether the rent covers the mortgage.
It is whether the property can generate an attractive return after accounting for all income, expenses, financing costs, risks, and long-term wealth drivers.
A rental property may look profitable when someone compares only two numbers:
- Monthly rent
- Monthly mortgage payment
But that comparison is incomplete.
An investor may also need to account for:
- Property taxes
- Landlord insurance
- Property management
- Repairs and maintenance
- Homeowners association fees
- Vacancy
- Tenant turnover
- Leasing costs
- Financing terms
- Closing costs
- Future refinancing
- Selling costs
This is why rent minus mortgage is not true cash flow.
True cash flow is what remains after the property’s relevant operating and financing expenses have been considered.
A property can collect more rent than its mortgage payment and still lose money.
It can also produce modest cash flow today while building substantial wealth over time.
That is why serious investors look beyond the first month.
Why Monthly Payment Thinking Can Be Misleading
Monthly payment thinking focuses on affordability.
Investment thinking focuses on performance.
Those are not the same thing.
A buyer purchasing a primary residence may reasonably ask:
- Can I make this payment comfortably?
- Is this the right neighborhood for my family?
- Do I like the layout?
- Is the commute manageable?
An investor must ask different questions:
- Who is the ideal tenant?
- What rent can the market support?
- What expenses will reduce income?
- How sensitive is the investment to interest rates?
- What happens if the property is vacant?
- What assumptions are driving the projection?
- How much equity may build over time?
- What is the expected return on invested capital?
- How does this asset fit into the broader portfolio?
The house may be the same.
The decision framework is completely different.
How Does a Rental Property Build Wealth?
A well-selected rental property can build wealth through several mechanisms at the same time.
At BricksFolios, we explain this through the BricksFolios IDEAL framework.
What Does IDEAL Stand For in Real Estate Investing?
IDEAL stands for:
- Income
- Depreciation
- Equity
- Appreciation
- Leverage
Each component represents a different way real estate may contribute to an investor’s financial outcome.
One asset can potentially activate all five.
That is what makes real estate structurally different from many other investments.
1. Income
Income is the rent collected from tenants.
After paying operating expenses and financing costs, the remaining amount may become cash flow.
Income matters because it can:
- Support the mortgage
- Cover property expenses
- Create monthly cash flow
- Reduce the investor’s out-of-pocket burden
- Strengthen long-term returns
However, income is only one part of the investment.
A property should not automatically be rejected because its first-year cash flow appears modest.
The investor must also examine what is happening to equity, appreciation, taxes, and debt reduction.
2. Depreciation
Depreciation is a tax deduction that allows an investor to recognize the gradual wear and aging of the building over time.
It is often described as a paper expense because the investor may receive a deduction without writing a check for that exact amount in that year.
This may help reduce taxable rental income.
For high-income W-2 professionals, depreciation is often one of the least understood parts of real estate investing.
Many employees are familiar with salary, bonuses, stock compensation, and retirement accounts.
They may be less familiar with how the tax code treats business ownership and income-producing assets.
Depreciation does not make a bad investment good.
It can, however, improve the after-tax outcome of a well-structured investment.
Tax treatment depends on individual circumstances, income levels, participation rules, and current law. Investors should work with a qualified tax professional.
3. Equity
Equity is the difference between the property’s value and the remaining debt.
Equity can grow when:
- The investor makes a down payment
- The mortgage principal is reduced
- The property value increases
- Additional improvements increase the property’s value
One of the most powerful features of rental real estate is that the tenant’s rent helps support the loan payment.
A portion of the mortgage payment may reduce principal.
Over time, that principal reduction can increase the investor’s ownership stake.
The investor owns the asset.
The tenant helps pay for it.
That is a very different wealth-building mechanism from purchasing an asset that does not produce income.
4. Appreciation
Appreciation is the increase in the property’s market value over time.
Equity and appreciation are related, but they are not identical.
Appreciation refers to the increase in the asset’s value.
Equity reflects the owner’s financial interest after subtracting debt.
For example, equity may increase because:
- The property appreciates
- The mortgage balance declines
- Both happen at the same time
This dual effect can become increasingly powerful over longer holding periods.
Appreciation is never guaranteed.
That is why market selection, tenant demand, employment stability, supply constraints, and local economic fundamentals matter.
5. Leverage
Leverage means using borrowed money to control a larger asset.
An investor may contribute a portion of the purchase price as a down payment and finance the remaining amount.
This allows the investor to benefit from the performance of the entire property, not merely the cash initially invested.
Leverage can amplify returns.
It can also amplify losses.
That is why leverage must be used carefully.
The right question is not whether debt is good or bad.
The right question is whether the debt is sustainable, strategically structured, and supported by the income and quality of the asset.
Why Can a Low-Cash-Flow Property Still Build Significant Wealth?
A property with modest first-year cash flow may still build meaningful wealth if several other factors are working in the investor’s favor.
These may include:
- The tenant paying down principal
- Property value appreciation
- Rent growth
- Tax benefits
- Favorable financing
- Refinancing opportunities
- Long holding periods
- Reinvested cash flow
This is where many people misread real estate.
They focus only on the amount left over each month.
But monthly cash flow may be only the visible portion of the return.
The larger wealth creation may occur quietly through equity accumulation and appreciation.
That does not mean cash flow is unimportant.
Cash flow provides a margin of safety.
It helps absorb repairs, vacancy, and unexpected costs.
The broader lesson is that investors should evaluate the complete return profile rather than relying on one metric.
How Do Interest Rates Change a Real Estate Investment?
Interest rates can significantly affect:
- Monthly mortgage payments
- Cash flow
- Total interest expense
- Return on invested capital
- Refinancing options
- The price an investor can reasonably pay
Two investors can purchase similar properties at similar prices and receive very different outcomes because of financing.
A lower interest rate may:
- Reduce the monthly payment
- Improve cash flow
- Increase the investor’s margin of safety
- Make the property easier to hold
- Improve long-term returns
This is why professional investment analysis must include actual financing assumptions.
A generic mortgage estimate may not reflect:
- Investor down payment requirements
- Builder incentives
- Adjustable-rate mortgage structures
- Discount points
- Refinancing strategies
- Closing costs
- Loan-specific restrictions
The property matters.
The financing also matters.
Sometimes, financing is what turns an average opportunity into a compelling one.
How Does Real Estate Hedge Against Inflation?
Real estate may help protect investors from inflation because income and asset values can rise while certain debt payments remain relatively stable.
There are several mechanisms at work.
1. Rent May Increase
As wages and living costs rise, market rents may also increase.
Higher rent can improve income over time, provided expenses do not rise faster.
2. Property Values May Increase
Inflation can increase the cost of land, labor, materials, and new construction.
As replacement costs rise, existing properties may become more valuable.
3. Fixed Debt Can Become Cheaper in Real Terms
A fixed mortgage payment may remain unchanged while rents, wages, and property values increase.
The nominal payment is the same.
Its real economic burden may decline over time.
4. Land Is Limited
Land cannot be manufactured.
In desirable areas with strong employment, population growth, and restricted housing supply, this scarcity can support long-term value.
Real estate is not a perfect inflation hedge.
Insurance, taxes, repairs, and financing costs may also increase.
The property must still be purchased at a sensible price and supported by durable demand.
The deeper point is that owning an income-producing asset may respond differently to inflation than holding cash alone.
Cash loses purchasing power when prices rise.
A productive asset has the potential to adjust.
What Is the Power of Compounding in Real Estate?
Compounding occurs when growth builds on prior growth.
In rental real estate, multiple forms of compounding may happen simultaneously.
Rent Compounding
If rent increases over time, each future increase is calculated from a higher base.
Appreciation Compounding
If a property rises in value annually, future appreciation may be calculated on the new, higher value.
Equity Compounding
As principal is reduced and property value grows, the investor’s equity may expand from two directions.
Reinvestment Compounding
Cash flow can potentially be:
- Used to reduce the mortgage
- Saved for another down payment
- Reinvested into improvements
- Redeployed into another asset
This is why time matters so much.
The early years may not look dramatic.
The curve often becomes more powerful later because multiple wealth drivers are building on one another.
Compounding rewards patience.
It also rewards quality.
Time does not rescue a bad asset.
Time magnifies the result of the asset selected.
What Is the Difference Between a Real Estate Portal and an Investment Analysis Platform?
Traditional real estate portals and investment analysis platforms serve different purposes.
They should not be viewed as competitors performing the same job.
They are better understood as tools for different stages of the process.
What Traditional Real Estate Portals Do Well
Platforms such as Zillow, Redfin, Realtor.com, Trulia, and Compass are valuable for:
- Discovering properties
- Reviewing listing photos
- Comparing asking prices
- Exploring neighborhoods
- Monitoring market activity
- Reviewing property facts
They help users understand what is available.
That is an important part of the process.
What BricksFolios Smart LTR Adds
BricksFolios Smart LTR (Long Term Rental Analysis) is designed to help an investor evaluate a property as a financial asset.
It brings together:
- Purchase assumptions
- Starter costs
- Rental income
- Operating expenses
- Financing
- Cash flow
- Refinance scenarios
- Equity growth
- Appreciation
- Long-term wealth projections
- Year-by-year assumptions
The distinction is simple:
Real estate portals help people find properties.
Smart LTR helps investors evaluate whether those properties fit their financial goals.
Finding a property is the easy part.
Determining whether it deserves your capital is the real work.
How Does BricksFolios Reduce Guesswork in Real Estate Investing?
Real estate investing often feels fragmented.
An investor may need to gather information from:
- Listing portals
- Lenders
- Property managers
- Insurance agents
- Tax professionals
- Contractors
- Rental data sources
- Spreadsheet models
Each source may use different assumptions.
That creates friction.
It also creates room for errors.
BricksFolios Smart LTR reduces guesswork by organizing critical investment inputs into one structured analysis.
This can help investors:
- Smart Comps: Price for offer strategy – evaluate like an appraiser
- Smart Comps: Rent for rent strategy – know what rent you can actually ret
- See the full cost of ownership
- Compare scenarios
- Understand financing impact
- Test long-term assumptions
- Evaluate cash flow
- Review projected wealth creation
- Make decisions using a consistent framework
The goal is not to remove judgment.
The goal is to improve judgment.
Technology does not replace the investor.
It gives the investor a better decision-making system.
That is what makes real estate begin to feel more like evaluating a stock or portfolio asset.
The investor can move from scattered information to a clearer financial picture, and invest like professional institutional investors.
Why This Matters for High-Income W-2 Professionals
Many high-income professionals are excellent at earning money.
They are not always taught how to convert income into durable ownership.
This is especially true for technology professionals whose financial lives may be heavily concentrated in:
- Salary
- Employer stock
- Retirement accounts
- Public equities
- One primary residence
That concentration can create hidden risk.
The employer may provide the paycheck, stock compensation, health insurance, career identity, and a large portion of the investment portfolio.
Real estate can provide a different source of wealth creation.
It may offer:
- Income outside employment
- Tax-efficient ownership
- Portfolio diversification
- Inflation protection
- Equity growth
- A path toward financial independence
The objective is not to abandon stocks.
The objective is to avoid building an entire financial future around one employer, one asset class, or one source of income.
Why This Matters for Parents
Parents often focus on helping children succeed academically.
That matters.
Strong grades, discipline, and credentials can open doors.
But the next generation also needs a practical understanding of:
- Credit
- Debt
- Taxes
- Ownership
- Risk
- Compounding
- Investing
- Cash flow
- Opportunity cost
A student can graduate from a top university without knowing how to evaluate a mortgage, rental property, business, or investment.
That gap has real consequences.
The earlier a young person understands ownership, the more time compounding has to work.
The purpose of teaching students real estate analysis is not to convince every student to become a landlord.
It is to teach them how capital works.
It is to help them ask better questions.
It is to help them understand that income is only the beginning.
Wealth is built through what they own, how they allocate capital, and how long they allow good decisions to compound.
What Our Interns Learned in Session 3
During Session 3, students explored:
- Why rent minus mortgage is not true cash flow
- How financing changes investment outcomes
- How the IDEAL framework explains real estate wealth creation
- Why modest cash flow can still support strong long-term returns
- How appreciation and principal reduction build equity
- How rental property may hedge against inflation
- How compounding becomes more powerful over time
- How property discovery differs from investment analysis
- How Smart LTR helps investors evaluate opportunities using data
The students were not asked to memorize formulas.
They were asked to think.
That is a more valuable skill.
The Bigger Lesson: Learn to Evaluate Assets, Not Just Buy Things
Most consumers ask:
- Can I afford it?
- What is the payment?
- Do I like it?
- Can I qualify?
Investors ask:
- What does it produce?
- What does it cost?
- What assumptions drive the return?
- What are the risks?
- How does it build value?
- How does it fit my portfolio?
- What happens over time?
That shift from consumer thinking to ownership thinking changes everything.
The goal is not simply to buy real estate.
The goal is to own the right asset, with the right financing, in the right market, for the right reason.
A monthly payment tells you whether you may be able to buy.
A complete investment analysis tells you whether you should.
Frequently Asked Questions
Is rent minus mortgage the same as cash flow?
No. True cash flow should account for relevant operating and financing expenses, including taxes, insurance, management, maintenance, vacancy, and other property-specific costs.
What is the IDEAL framework in real estate?
IDEAL stands for Income, Depreciation, Equity, Appreciation, and Leverage. It explains five ways a rental property may contribute to wealth creation.
How does a rental property create wealth?
A rental property may create wealth through cash flow, mortgage principal reduction, appreciation, tax benefits, rent growth, and the strategic use of leverage.
Can a property with low monthly cash flow still be a good investment?
Yes. A property with modest cash flow may still build significant wealth through equity growth, appreciation, tax efficiency, and long-term rent growth. The full risk and return profile must be evaluated.
How does real estate hedge against inflation?
Real estate may hedge against inflation because rents and property values can rise while fixed mortgage payments remain stable. Limited land and higher replacement costs may also support values.
What is the difference between equity and appreciation?
Appreciation is the increase in property value. Equity is the owner’s financial interest in the property after subtracting outstanding debt.
Why is depreciation valuable to real estate investors?
Depreciation may reduce taxable rental income by allowing the investor to deduct a portion of the building’s value over time. Individual tax outcomes vary.
How do interest rates affect rental property returns?
Interest rates affect mortgage payments, cash flow, total interest costs, and the investor’s return. A lower rate can materially improve the economics of the same property.
What does BricksFolios Smart LTR do?
Smart LTR helps investors analyze rental properties by combining income, expenses, financing, cash flow, refinancing scenarios, equity, appreciation, and long-term wealth projections.
Are real estate portals still useful for investors?
Yes. Real estate portals are valuable for discovering properties, researching neighborhoods, reviewing listings, and monitoring the market. Smart LTR serves a complementary role by helping evaluate the investment potential of a property.
Final Takeaway
“Can I afford the payment?” is not a bad question.
It is simply an incomplete one.
Affordability tells you whether a transaction may be possible.
Investment analysis tells you whether the transaction may be worthwhile.
The better question is:
Will this asset actually build wealth?
That is the question investors ask.
That is the question more parents should teach.
And that is the question the next generation must learn to answer.
Ready to See Whether Real Estate Can Accelerate Your Wealth Strategy?
Finding a promising property is only the first step.
The real challenge is determining whether it is the right asset, in the right market, with the right financing, for your long-term financial goals.
BricksFolios is a real estate wealth-tech platform built for high-income professionals who want the benefits of real estate ownership without having to become full-time investors, analysts, landlords, or property managers.
Our proprietary platform help remove the guesswork from investing by evaluating the complete financial picture:
Income.
Operating expenses.
Financing.
Cash flow.
Tax efficiency.
Equity growth.
Appreciation.
Long-term wealth potential.
But technology is only one part of the experience.
Our end-to-end, white-glove service supports investors throughout the entire journey. From portfolio planning, market selection, property sourcing, and financial analysis to financing, acquisition, leasing, property management, tax strategy coordination, and eventual exit planning.
You make the investment decisions with our expert help.
BricksFolios helps manage the complexity behind them.
The result is a more structured, data-driven way to build wealth with real estate. One designed to make owning investment properties almost as easy as investing in stocks, while preserving the powerful benefits of a tangible, income-producing asset.
Do not simply ask:
“Can I afford the payment?”
Ask:
“Will this asset actually build wealth?”
Schedule a strategy session with the BricksFolios founders:


Leave a Reply