
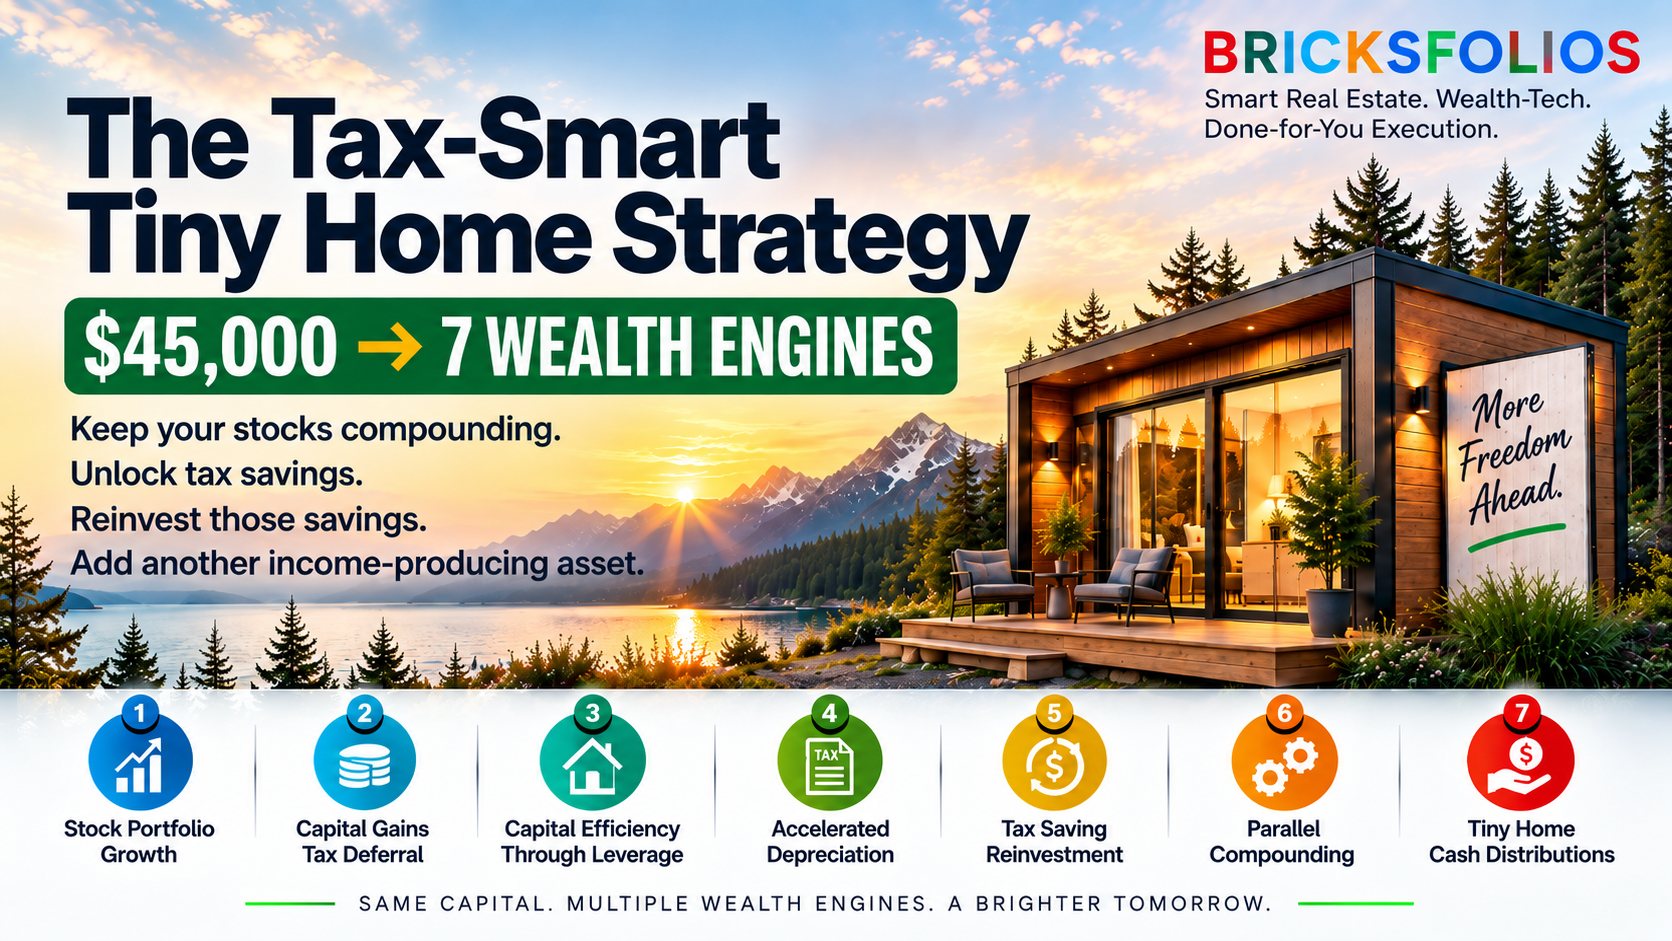
See how $45K of investment capital can potentially unlock $50K tax savings and activate 7 wealth engines. Additional FFE and fees apply.
Keep your stocks compounding. Unlock tax savings. Reinvest those savings. Add another income-producing asset.
Most high-income professionals think about investing sequentially.
You save money.
You invest it.
Then you wait for that investment to grow before deploying capital again.
But what if the same financial decision could activate multiple wealth engines at the same time?
Your stock portfolio continues compounding.
Borrowed capital helps fund a Tiny Home investment.
The Tiny Home may generate substantial depreciation.
That depreciation may create meaningful tax savings for qualifying investors.
Instead of spending those tax savings, you put them back to work.
And the underlying Tiny Home investment can generate cash distributions.
This is the idea behind the BricksFolios Tax-Smart Tiny Home Strategy, powered by BricksFolios Parallel Compounding™.
The objective isn’t simply to buy another investment.
The objective is to make the capital you already have work harder.
Why Now: OBBBA Changed the Tax Equation
For high-income investors, the One Big Beautiful Bill Act, or OBBBA, changed the tax landscape.
OBBBA restored 100% bonus depreciation for certain qualifying property acquired and placed in service after January 19, 2025. Under current IRS guidance, eligible property can potentially receive a 100% first-year depreciation deduction, subject to the property’s tax classification and the investor’s individual circumstances.
That matters because depreciation isn’t simply an accounting benefit.
For a qualifying investor who can utilize the deduction, accelerated depreciation may reduce taxable income today.
That can leave more capital available to invest rather than send to taxes.
And that creates a different wealth-building cycle:
Earn income → Invest in productive assets → Generate potential deductions → Preserve more capital → Reinvest the tax savings → Compound again
An eligible investment placed in service in 2026 may potentially generate depreciation in 2026.
Those potential tax savings can then become investment capital for 2027.
That capital gets another year to work.
Another year to compound.
And potentially another opportunity to acquire productive assets.
Wait until 2027, and you haven’t simply postponed an investment by twelve months.
You may have postponed:
The deduction.
The tax savings.
The reinvestment.
And the next turn of the compounding cycle.
You can’t compound yesterday’s tax savings.
Why This Matters for High-Income Tech Professionals
Technology professionals often appear highly diversified because they own many investments.
But look underneath the surface.
Salary comes from tech.
Bonus comes from tech.
RSUs come from tech.
Future vesting comes from tech.
The 401(k) is largely invested in public markets.
The brokerage portfolio may be heavily concentrated in technology.
And household lifestyle expenses still depend on continued W-2 income.
That’s not necessarily true diversification.
It can be multiple forms of exposure to the same economic engine.
Then add taxes.
High-income professionals can lose a significant portion of every additional dollar earned to federal and potentially state taxes before that capital ever gets a chance to compound.
The result?
Many professionals become exceptionally good at earning wealth without building a system that allows more of that wealth to work independently of their careers.
A tax-smart real estate strategy can potentially introduce something different:
Income.
Tax efficiency.
Leverage.
Diversification – alternative asset exposure.
And another wealth engine outside your employer and the stock market.
The Problem With Traditional Investing
Imagine you have a sizable stock portfolio and want to diversify into real estate.
The obvious approach is:
Sell stocks → generate cash → invest the cash into real estate.
Simple.
But potentially expensive.
Selling appreciated stock can trigger capital-gains taxes.
More importantly, the shares you sold can no longer participate in future stock-market growth.
You turned off one wealth engine to start another.
That is exactly what Parallel Compounding™ attempts to avoid.
Instead of asking:
“Which asset should I invest in?”
We ask:
“How can the same balance sheet support multiple wealth engines simultaneously?”
That distinction can materially change how capital compounds over time.
Example
Consider a hypothetical high-income technology professional evaluating a Tax-Smart Tiny Home investment.
The assumptions
| Assumption | Example |
|---|---|
| Initial Tiny Home investment downpayment | $30,000 |
| Furniture, Fixtures & Equipment (FFE) | $15,000 |
| Investment horizon | 10 years |
| Potential qualifying depreciation | $135,000 |
| Illustrative marginal tax rate | 37% |
| Potential tax savings | $49,950 |
| Existing stock portfolio | $100,000 |
| Illustrative borrowing capacity against securities | $50,000 |
| Illustrative borrowing rate | 8% |
| Assumed stock growth | 10% annually |
| Tax savings reinvestment assumption | 8% annually |
Note: BricksFolios fees and third-party legal fees also apply and are not included in the amounts shown above. Actual costs, financing terms, FFE requirements, fees, and investment structure may vary.
Now look at what may happen when these pieces are coordinated instead of evaluated independently.
There isn’t one wealth engine.
There are seven.
Wealth Engine One: Keep Your Stock Portfolio Compounding
For many technology professionals, a significant portion of net worth sits in company stock, RSUs, ETFs, or other securities.
When they decide to invest in real estate, their first instinct is often:
Sell some stock.
But selling stock has an opportunity cost.
Suppose $60,000 of stock could instead remain invested.
At an illustrative 10% annual growth rate, $60,000 compounded for ten years would grow to approximately:
$155,625
That’s over $95,000 of potential growth above the original $60,000.
Of course, markets don’t grow at 10% every year. Returns aren’t guaranteed.
But the principle matters.
Every dollar of appreciated stock you sell today is a dollar that can no longer compound for you tomorrow.
Parallel Compounding™ starts by asking whether that wealth engine really needs to be turned off.
Wealth Engine Two: Potential Capital-Gains Tax Deferral
There’s another potential consequence of selling appreciated stock.
Taxes.
Suppose part of your stock portfolio has accumulated substantial unrealized gains.
Selling those shares to fund another investment may create an immediate taxable event.
Instead, depending on the investor’s circumstances and financing options, accessing capital without selling those securities may allow the investor to defer realizing those gains.
That means more capital can potentially remain invested.
The exact benefit depends on your cost basis, taxable gains, federal and state tax rates, and individual circumstances.
But this is an important distinction.
Selling an asset to fund another asset can create three costs:
- The capital leaves the original investment.
- Future compounding on that capital stops.
- A taxable gain may be triggered.
Those costs should be considered before liquidating appreciated assets.
Wealth Engine Three: Capital Efficiency Through Leverage
Now we introduce leverage.
Instead of contributing the full cost of an investment in cash, financing can allow an investor to control a substantially larger productive asset with a smaller amount of initial capital.
In our example:
Initial cash investment: $45,000
But the potential depreciable asset base modeled is:
$135,000
That difference matters.
The goal isn’t maximum debt.
The goal is capital efficiency.
A mortgage can allow an investor to acquire an income-producing asset while preserving capital for other investments, reserves, or opportunities.
Used intelligently, leverage can give the same dollar more than one job.
Used poorly, leverage magnifies risk.
That’s why financing should be part of an overall portfolio strategy, not simply a way to minimize the down payment.
Wealth Engine Four: Accelerated Depreciation
This is where the Tiny Home strategy becomes especially interesting for certain high-income investors.
Real estate investors often think of depreciation as a small annual deduction spread over decades.
But certain qualifying assets may be eligible for significantly accelerated depreciation depending on their classification, the applicable tax rules, and the investor’s circumstances. Current IRS instructions provide a 100% special depreciation allowance for qualifying property acquired after January 19, 2025.
The tax classification of a Tiny Home used for transient lodging can differ from that of conventional residential rental real estate.
Consider our example.
Potential qualifying depreciation:
$135,000
Assume, purely for illustration, that the investor is able to use the entire deduction and has a 37% marginal tax rate.
The potential tax impact would be:
$135,000 × 37% = $49,950
That’s:
$49,950 of potential tax savings
against an initial investment of:
$45,000
Read that again.
The potential tax savings in this illustration are greater than the investor’s original cash contribution.
That’s possible because the investor’s depreciation deduction isn’t necessarily limited to the amount of cash initially invested.
The asset’s depreciable basis, financing structure, ownership structure, tax classification, basis limitations, at-risk rules, passive-activity rules, and the investor’s ability to utilize the deduction all matter.
This is precisely why tax-smart real estate investing isn’t simply about buying a property.
Structure matters.
Wealth Engine Five: Tax Saving Reinvestment™
Here’s where most tax strategies stop too early.
Imagine generating $49,950 of tax savings.
What happens next?
For many households, those dollars quietly disappear into lifestyle spending.
A vacation.
A new car.
Home improvements.
A larger checking-account balance.
The tax strategy worked.
But the wealth strategy stopped.
At BricksFolios, we think about it differently.
Don’t just save the tax. Reinvest the tax savings.
Suppose the hypothetical $49,950 tax savings were invested and earned an illustrative 10% annual return over the following nine years.
That capital could potentially grow to approximately:
$117,779
A one-time tax benefit has now become another compounding asset.
That’s Tax Saving Reinvestment™.
The traditional question is:
“How much can I save in taxes?”
The better wealth-building question is:
“What will those tax savings become if I never spend them?”
That’s a dramatically different way to think about tax planning.
Tax Savings
$49,950 saved once.
Tax Saving Reinvestment™
$49,950 potentially compounds toward approximately $118K.
Same initial tax strategy.
Very different long-term outcome.
Wealth Engine Six: Parallel Compounding™
Now bring everything together.
Your stock portfolio can remain invested.
Your Tiny Home investment operates independently.
Potential tax savings can be reinvested into another asset.
Each pool of capital is now working on a different track.
Stock capital is compounding.
Tax savings are compounding.
The underlying Tiny Home investment is operating.
Instead of waiting for one asset to finish producing wealth before beginning another investment, you’re potentially allowing multiple assets to compound in parallel.
That’s Parallel Compounding™.
Think about the difference.
Traditional investing
Capital → Investment A → Growth → Sell → Investment B
One engine at a time.
Parallel Compounding™
Existing Assets → Continue Compounding
Borrowed Capital → New Productive Asset
Tax Savings → Reinvestment
Investment Operations → Cash Distributions
Multiple engines.
Working simultaneously.
That is how balance-sheet strategy can become more powerful than simply chasing the highest individual investment return.
Wealth Engine Seven: Tiny Home Cash Distributions
Finally, there’s the underlying asset itself.
While the other wealth engines focus on capital efficiency, tax strategy, and compounding, the Tiny Home investment is also designed to generate cash distributions from its operations.
That creates another potential source of return alongside the tax and compounding benefits already discussed.
Actual distributions will depend on the specific investment opportunity, operating performance, financing, reserves, expenses, and other factors.
The larger point is simple.
Your capital doesn’t have to depend on one wealth engine.
Multiple financial engines can potentially be working at the same time.
The BricksFolios Tax Savings Flywheel™
When Today’s Tax Savings Help Buy Tomorrow’s Assets
Tax Saving Reinvestment™ becomes much more powerful when you stop thinking about it as a one-time event.
Consider what could happen when the process is repeated.
For illustration, assume an investor has the capital, tax profile, eligibility, and financing capacity to acquire two Tax-Smart Tiny Home investments in 2026.
2026: Start the Flywheel
The investor deploys capital into:
2 Tiny Homes
Those investments may potentially generate substantial first-year depreciation.
Instead of treating the resulting tax savings as extra spending money, the investor redeploys them.
Tax savings become capital for the next investment cycle.
2027: Reinvest Into Two More
Potential tax savings generated from the 2026 investments are redeployed to help fund:
+2 Tiny Homes
Potential portfolio:
4 Tiny Homes
Those 2027 investments may potentially generate their own eligible depreciation.
Which may create another round of tax savings.
Instead of consuming those savings, the investor redeploys them again.
2028: Turn the Flywheel Again
Potential tax savings generated from the 2027 investments are redeployed toward:
+2 Tiny Homes
Potential portfolio:
6 Tiny Homes
The original capital decision made in 2026 has now helped create subsequent investment capacity.
Not simply because the investor saved more from each paycheck.
Because earlier investment decisions potentially helped create capital for later investments.
2029: Another Turn
The strategy repeats.
Potential tax savings generated from the 2028 investments are redeployed toward:
+2 Tiny Homes
Potential portfolio:
8 Tiny Homes
The illustrative progression:
| Year | New Tiny Homes | Potential Portfolio |
|---|---|---|
| 2026 | 2 | 2 |
| 2027 | +2 | 4 |
| 2028 | +2 | 6 |
| 2029 | +2 | 8 |
One investment cycle.
Then another.
Then another.
Then another.
The Tax Savings Flywheel
This may be the most important concept in the entire strategy.
Imagine the following sequence:
Earn income.
↓
Invest in productive assets.
↓
Generate eligible tax deductions.
↓
Reduce taxes when applicable.
↓
Reinvest the tax savings.
↓
Allow those investments to compound.
↓
Use growing assets to create additional investment capacity.
↓
Repeat.
Taxes stop being viewed only as an expense to minimize.
Tax efficiency becomes another potential source of investment capital.
That’s the flywheel.

And every time the capital gets redeployed instead of consumed, the wealth-building system gets another opportunity to compound.
The Real Goal Isn’t a Tiny Home
A Tiny Home is an asset.
It isn’t the objective.
The objective is to build a financial system in which more and more of your wealth is generated independently of your paycheck.
Your stocks compound.
Your real estate investments operate.
Your tax strategy potentially preserves more capital.
Your tax savings get reinvested.
Your assets generate additional income.
And over time, your dependence on W-2 income can begin to decline.
That’s the transition from:
High Income
to
High Net Worth
to eventually
Job-Optional Wealth.
The biggest mistake high-income professionals make isn’t necessarily choosing the wrong stock or buying the wrong property.
It’s allowing enormous amounts of capital to operate independently instead of designing a coordinated wealth system.
What Would This Look Like With Your Numbers?
The example above assumes:
$30,000 of initial down payment
A $100,000 stock portfolio
Potential access to $60,000 of capital against securities
$135,000 of potential depreciation
A 37% illustrative marginal tax rate
$49,950 of potential tax savings
Your numbers will be different.
Your W-2 income matters.
Your expected tax liability matters.
Your stock portfolio matters.
Your embedded capital gains matter.
Your available capital matters.
Your borrowing capacity matters.
Your ability to utilize depreciation matters.
And your long-term wealth goals matter.
That’s why the next step isn’t buying a Tiny Home from a blog.
The next step is determining whether the strategy actually fits your financial situation.
Book a 1:1 Real Estate Portfolio Strategy Call
During your strategy session, we’ll review your:
Existing investment portfolio
Available capital
2026 tax situation
Stock and RSU exposure
Potential funding options
Real estate portfolio goals
Long-term financial objectives
Then we’ll model how a Tax-Smart Tiny Home strategy could potentially fit into your broader real estate portfolio.
If the economics make sense and you’re ready to deploy capital, we’ll show you the next steps to put that capital to work.
Build wealth that doesn’t depend on your next paycheck.
Book your 1:1 Real Estate Portfolio Strategy Call:
STR.BricksFolios.com
Disclaimer
For educational and informational purposes only. This content does not constitute tax, legal, investment, financial, accounting, or lending advice. The examples, assumptions, calculations, and projections presented are illustrative only and are not guarantees of future results.
Tax treatment, depreciation eligibility, and the ability to utilize deductions or losses depend on each investor’s individual circumstances, including tax basis, at-risk limitations, passive-activity rules, material participation, the nature of the rental activity, and other applicable tax rules. Investment returns, distributions, financing costs, and other outcomes may vary. Tax laws and regulations may change.
Illustrative investment amounts do not include all costs. Furniture, Fixtures & Equipment (FFE), BricksFolios fees, legal fees, financing costs, reserves, and other transaction or operating expenses may apply and will vary by investment.
Please consult your CPA, tax advisor, attorney, financial advisor, lender, and other qualified professionals regarding your specific circumstances before making any investment, financing, legal, or tax decision.